

Salon and barbershop contents insurance
Barbershop Contents and Fit-out Insurance
A barbershop costs a lot to fit out: hydraulic chairs, basins, mirrors, lighting, a counter and the plumbing behind it all. Insurers call this commercial property cover, and it pays to put the shop back together after damage.
Your policy can cover storm and fire, theft, glass, money, equipment breakdown and the fit-out itself.
Cover is subject to the policy terms and the insurer's acceptance.
Reviewed by
Founder and Director, Grace Insurance. Diploma in Broking, Fellow CIP. In insurance broking since 1992.
What contents cover pays for
What Contents and Fit-out Cover Pays For
Contents and fit-out cover pays to repair or replace what is in your shop, and what you built into it, after fire, storm, a burst pipe or a break-in. Glass, money and equipment breakdown are parts you can add, and you choose which ones go on your policy.
Storm and fire
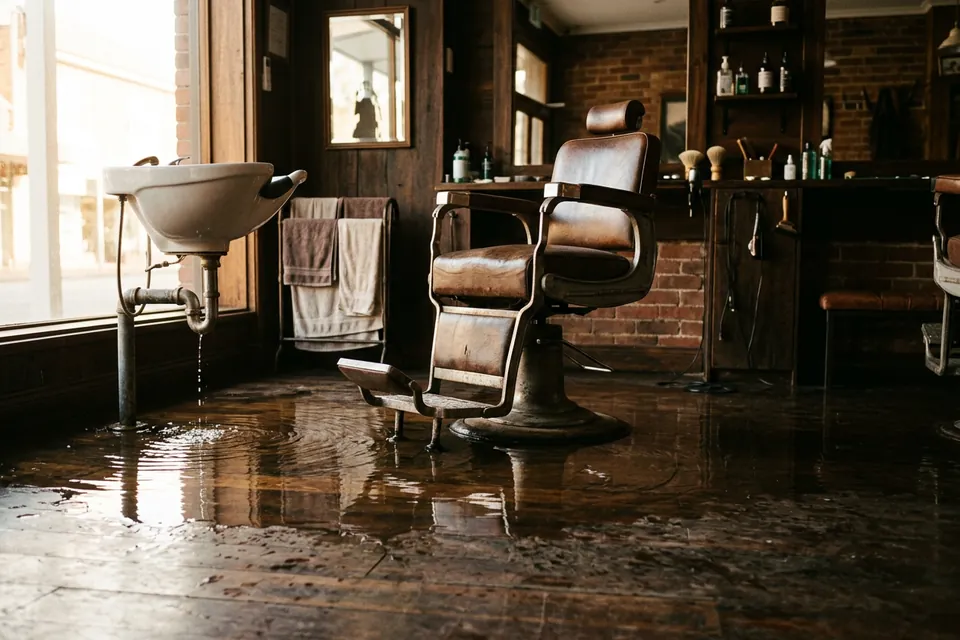
Fire, storm, lightning and water from a burst pipe are the main things the cover pays for. It pays to repair or replace damaged chairs, mirrors, stock and furniture.
Flood, meaning water rising from a river, creek or the sea, is not always covered the same way as storm. Your quote shows whether it is included, so check for it if your shop sits in a low area.
Theft and break-ins
Theft cover pays for contents and stock taken in a break-in, and for the damage done getting in. It usually needs signs of forced entry, so lock up and set the alarm.
Glass
Glass cover pays to replace a broken shopfront window, glass door or mirror, and usually to board up the shop until it is fixed. Many leases make you responsible for the shopfront glass, so read yours.
Money
Money cover pays for cash stolen from the till, the safe or on the way to the bank, up to the amount on your policy. It matters if clients still pay cash for cuts and tips.
Equipment breakdown
Electronic equipment cover, also called equipment breakdown, pays to repair or replace electronic items that break down, such as the computer, EFTPOS terminal and booking tablet. Standard contents cover pays for damage from outside causes, not for a machine failing on its own.
Your fit-out
The fit-out is everything you built into a leased shop: benches, basins, plumbing, lighting, flooring and signage. If a fire destroys the inside of the shop, the landlord's policy covers the building, and yours covers the fit-out you paid for.
Lease insurance requirements
What Insurance Does Your Shop Lease Ask For?
01Read the insurance clause
Leases commonly ask for public liability at a set limit and glass cover for the shopfront, so read the insurance clause in yours. They also ask for proof on a certificate of currency, a short document from your insurer that shows your cover is active.
02If you own the building
We arrange cover whether you own the building or lease the shop. If you own it, the building itself can go on the same policy as your contents.
03We match the policy to your lease
Send us the insurance clause from your lease and we will set the policy up to match it.
Contents insurance cost
What Affects the Price of Contents and Fit-out Cover?
Your premium, the price of the policy, depends on your sums insured, where the shop is, your security, the parts you choose, the building and your excess. The exact figure is confirmed on your quote.
Your sums insured
The sum insured is the most the policy will pay. Set it at what it would cost to replace everything new today, because if it is too low, the insurer can pay less than your claim.
Where the shop is
The suburb, its storm and flood exposure, and local crime all count.
Your security
Alarms, deadlocks, cameras and a safe for cash can lower the price.
The parts you choose
Each extra part you add, such as glass, money or equipment breakdown, adds to the premium.
The building
What the building is made of, how old it is and what businesses run next door all affect the fire risk.
Your excess and claims history
The excess is the amount you pay towards each claim. A higher excess usually lowers the premium, and recent claims can raise it.
You can pay the premium in one go, or spread it with premium funding, where a finance company pays the insurer for you and you repay it weekly, fortnightly, monthly, quarterly or every six months.
Who it is for
Who Needs Contents and Fit-out Cover?
You need it if you own the chairs, stock and fit-out in a shop, which usually means barbershop owners and salon owners. If you rent a chair, the owner's contents cover usually does not include your things, so look at tools and equipment insurance instead.
Pair it with business interruption cover, which pays the income you lose while the shop is being repaired.
Related covers
Other Insurance for Barbershop Owners

Business Interruption
Covers the income you lose while the shop is closed after damage your policy covers, such as a fire.
Read about business interruption →
Public Liability
Covers claims from clients and the public for injury or damage to their property, with limits of $5 million, $10 million or $20 million.
Read about public liability →
Tools and Equipment
Insurers call it general property. It covers your clippers, scissors and styling tools against theft and damage.
Read about tools and equipment →Shop Contents and Fit-out FAQ
Contents and Fit-out Questions
Yes, barber chairs are contents. Set the sum insured, the most the policy pays, at what it would cost to buy the same chairs new today, including delivery and fitting.
It covers the improvements you paid for in a leased shop, such as basins, plumbing, benches, lighting and flooring. The landlord's building policy usually does not cover them.
Not always. Flood, meaning water rising from a river, creek or the sea, is not part of every policy, and your quote shows whether yours includes it. Check for it if your shop is near water or in a low area.
No. The landlord's policy covers the building they own, and your contents, stock and fit-out are yours to insure. The lease often says so.
Often, but check. Some glass cover is for the shopfront and doors only, so make sure internal mirrors are listed if you want them covered.
Contents insurance quote
Get a Contents and Fit-out Quote
Tell us about your shop, what it cost to fit out and what your lease asks for, and a broker will contact you with your options.
1800 556 777Monday to Friday, 8:30am to 5:00pm Perth time