

Personal accident insurance
Personal Accident and Illness Insurance for Barbers
A broken wrist, a bad back or a serious illness can stop you cutting for weeks. If you work for yourself, nobody pays you while you recover.
Personal accident and illness cover is the income cover you buy for yourself.
Cover is subject to the policy terms and the insurer's acceptance.
Reviewed by
Founder and Director, Grace Insurance. Diploma in Broking, Fellow CIP. In insurance broking since 1992.
What personal accident cover pays for
What Personal Accident and Illness Cover Pays For
Personal accident and illness cover pays you a regular amount while an injury or illness stops you working. Most policies cover you at work and away from it.
A broken wrist
A fall at the gym or on the footpath breaks your wrist, and you cannot hold the clippers for weeks. The policy pays your weekly benefit once the waiting period, the set number of days you must be off work first, is over.
A bad back or shoulder
Years of standing and leaning over the chair can catch up with you. Whether an injury that builds up over time is covered depends on the policy wording, the document that sets out what the policy covers, so ask us to check it before you buy.
An illness that keeps you home
If you choose accident and illness cover, not accident only, time off for a serious illness or surgery can be covered.
A permanent injury
If an accident leaves a permanent injury, such as losing the use of a hand, many policies pay a one-off lump sum on top of the weekly benefit.
The words on the policy
Terms to Understand Before You Buy
The weekly benefit, the waiting period, the benefit period and the rules on pre-existing conditions decide what a personal accident policy pays and when.
The weekly benefit replaces income
The weekly benefit is the amount the policy pays each week while you cannot work. It is usually capped at a share of your income.
The waiting period comes first
The waiting period is the number of days you must be off work before payments start. A shorter waiting period costs more.
Payments stop at the benefit period
The benefit period is the longest the policy will keep paying for one injury or illness. A longer benefit period costs more.
Past health problems may be excluded
Pre-existing conditions, health problems you had before the policy started, are usually left out, at least for a time. Tell the insurer about them when you apply.
Filling the gap
Personal Accident Cover and Workers Compensation
01Workers compensation covers your staff
Workers compensation covers your employees. It does not cover you if you are a sole trader, and it usually does not cover a chair renter working for themselves.
02Personal accident cover pays you
Personal accident and illness cover fills that gap for the person who owns the business. If you have staff and also cut hair yourself, you may need both.
Personal accident cost
What Affects the Price of Personal Accident Cover?
Your premium, the price of the policy, depends mostly on your age, the weekly benefit you choose and your waiting and benefit periods. Whether illness is included, your health and activities, and your claims history also count. The exact figure is confirmed on your quote.
Your age
Older people usually pay more, because the chance of injury and illness rises.
Your weekly benefit
A higher weekly payment costs more.
Waiting and benefit periods
A shorter wait and a longer benefit period both raise the premium.
Illness cover
Accident-only cover costs less than accident and illness together.
Your health and activities
Your medical history and risky sports or hobbies can change the price.
Your claims history
Recent claims can raise the premium.
You can pay the premium in one go, or spread it with premium funding, where a finance company pays the insurer for you and you repay it weekly, fortnightly, monthly, quarterly or every six months.
Who it is for
Who Needs Personal Accident and Illness Cover?
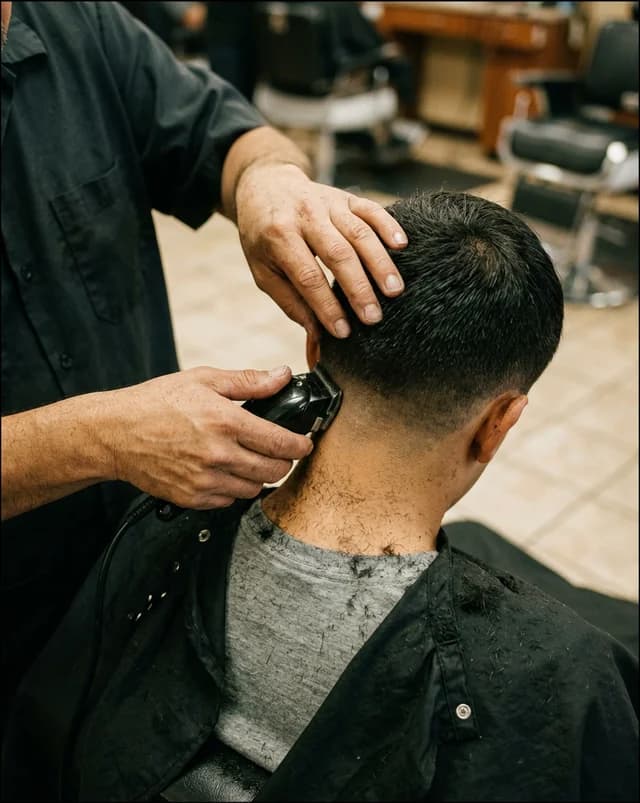
Self-employed barbers, chair renters and mobile barbers need it most, because their income stops when they stop working. Barbershop owners who cut in the shop themselves should look at it too.
If you already hold income protection through your superannuation fund, check what it pays and when before you add more.
Related covers
Covers That Sit Alongside Personal Accident
Workers Compensation
Covers wages and medical costs for employees hurt at work. Each state and territory sets its own rules.
Read about workers compensation →
Business Interruption
Covers the income you lose while the shop is closed after damage your policy covers, such as a fire.
Read about business interruption →
Tools and Equipment
Insurers call it general property. It covers your clippers, scissors and styling tools against theft and damage.
Read about tools and equipment →Personal Accident and Illness FAQ
Personal Accident Questions
They are similar. Personal accident and illness is usually a shorter-term cover renewed each year, and income protection is a longer-term life insurance product. Both pay a regular amount while you cannot work.
Most personal accident policies cover you at work and away from it. Check the policy wording for any activities it leaves out.
It starts paying after the waiting period you choose, which usually counts from the day a doctor says you cannot work. A shorter waiting period costs more.
Workers compensation covers your employees. It usually does not cover you as a sole trader. Personal accident cover is how you protect your own income.
Yes. Tell the insurer about past injuries and health conditions when you apply. They may be left out of the cover, but hiding them can put a claim at risk.
Personal accident quote
Get a Personal Accident Quote
Tell us what you earn and how long you could manage without pay, and a broker will contact you with your options.
1800 556 777Monday to Friday, 8:30am to 5:00pm Perth time