

Key points
- Public liability pays claims from clients and the public who are hurt or have things damaged.
- Treatment risk cover pays claims about the service you gave. Some insurers include it in professional indemnity and others add it to public liability.
- Tools cover pays to repair or replace stolen or damaged clippers, trimmers and scissors.
- Employers must hold workers compensation, and the rules vary by state and territory.
- Shop owners add cover for contents, fit-out and income lost while the shop is closed.
- Chair renters and mobile barbers need cover in their own name.
Which Covers Do Most Barbers Need?
Most barbers need public liability and cover for their tools. If you employ anyone, you also need workers compensation, which the law requires of employers.
The rest depends on how you work. A shop owner with staff needs more cover than a barber renting one chair, and a mobile barber carries risks a shop does not.
- Public liability: claims from people hurt, or whose things are damaged, because of your business.
- Professional indemnity: claims that a cut, shave, colour or treatment you gave caused harm.
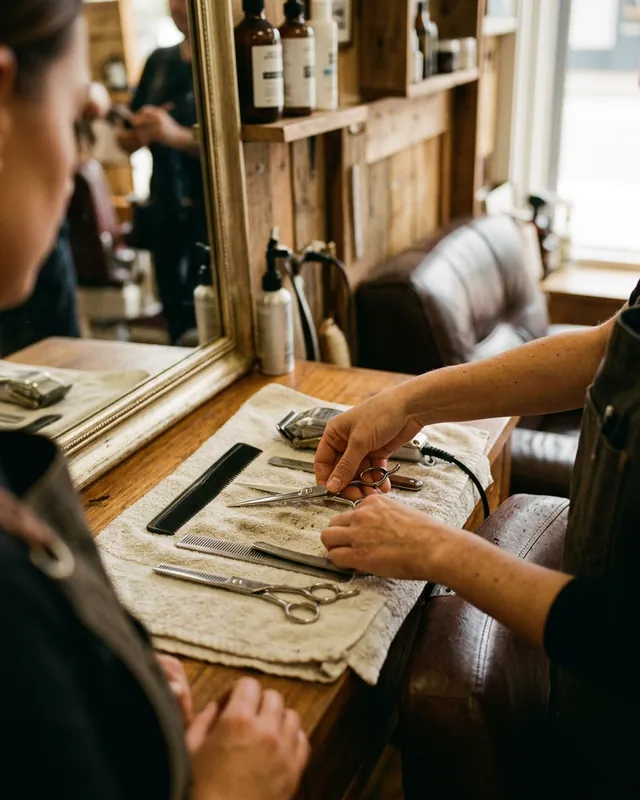
- Tools and equipment: your clippers, trimmers and scissors if they are stolen or damaged.
- Shop contents and fit-out: chairs, mirrors, stock and the fittings you paid for in the shop.
- Business interruption: the income you lose while the shop is closed after damage your policy covers.
- Workers compensation: wages and medical costs for an employee hurt at work.
Is Barber Insurance a Legal Requirement?
Workers compensation is the cover the law requires once you employ staff. For most barbers, the law leaves the other covers up to you. Some states and territories do require public liability for certain jobs.
In practice, other people often make cover a condition. A landlord, shopping centre or shop owner will usually ask to see your public liability before you start.
What Does Public Liability Cover for a Barber?
Public liability pays claims from people who are hurt, or whose belongings are damaged, because of your business. It also pays the legal costs of defending those claims, up to the limit on your policy.
In a barbershop, that could be a client who trips over a power cord or slips on wet tiles. It could also be a jacket ruined by bleach, or a client hurt by a falling mirror.
You can choose a limit of $5 million, $10 million or $20 million. Your limit is the most the insurer pays for one claim, so start with the figure your lease or chair agreement asks for.
What Is Treatment Risk Cover for Barbers?
Treatment risk cover pays claims that the service you gave caused harm. Some insurers include it in professional indemnity, the cover for claims about the quality of your work, and others add it to public liability.
Examples include an allergic reaction to beard dye, a burn from a hot towel or a cut from a straight razor. Check your quote shows it before you buy.
How Are a Barber's Clippers and Scissors Insured?
Clippers, trimmers, scissors and styling tools are insured under general property cover, the name insurers use for portable things you work with. It pays to repair or replace them after theft or accidental damage, usually in the shop or away from it.
A home or car policy may not pay for tools you use to earn money. Check its wording before counting on it, or ask us to look.
What Does a Barbershop Owner Need to Insure?
A shop owner usually adds contents, fit-out and business interruption cover to public liability. Contents cover pays for your chairs, mirrors, basins and stock, and fit-out is the benches, plumbing and lighting you paid to put in.
Business interruption pays the income you lose while the shop is closed after damage your policy covers, such as a fire or a burst pipe. Glass cover for the shopfront window and theft cover are often added to the same business policy.
These covers can be arranged whether you own the building or lease it. See insurance for barbershop owners for how they fit together.
When Does a Barber Need Workers Compensation?
You need workers compensation as soon as you employ someone. It pays wages and medical costs when an employee is injured or becomes ill because of their work.
Full-time, part-time and casual staff all count as workers, and so do apprentices and family members you employ. Each state and territory sets its own rules, including who provides the insurance.
Workers compensation does not cover you if you are a sole trader. For your own injury or illness, see personal accident and illness cover.
What Other Covers Do Barbers Add?
Barbers who work for themselves often add personal accident and illness cover, because there is no sick pay when you cannot cut hair. It pays you a regular amount while an injury or illness keeps you off work.
If clients book online or you keep their phone numbers and emails, cyber cover pays costs that follow a hack or data breach. Other covers we can arrange include money, electronic equipment, commercial vehicle and commercial legal expense cover.
Barber Insurance by How You Work
Shop owners, employed barbers, chair renters and mobile barbers each need a different mix of cover. It depends on whether you own the shop, work for someone, rent a chair or travel to clients.
- Shop owner: public liability, contents and fit-out, business interruption, and workers compensation for staff.
- Employed barber: your employer's policies usually cover your work in their shop, so ask them. Insure your own tools if you bring them.
- Chair renter: your own public liability, treatment risk and tools cover.
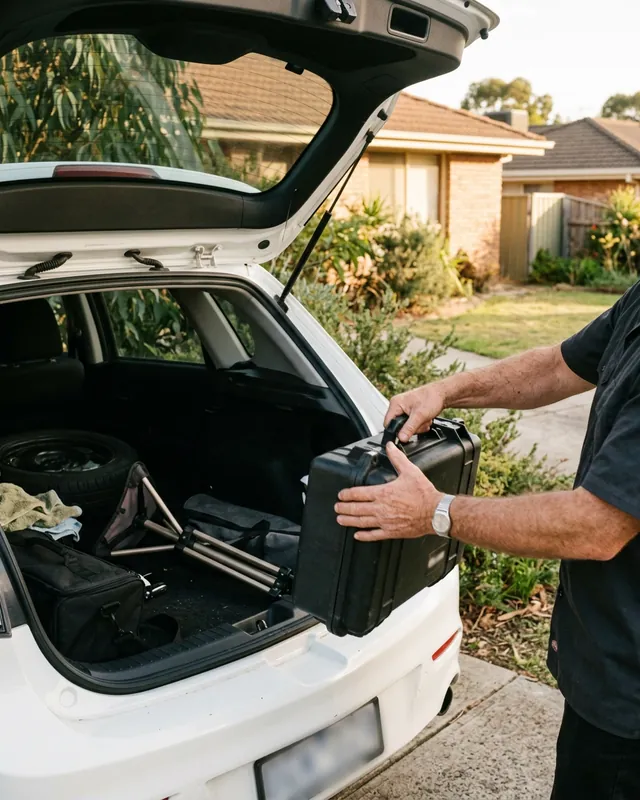
- Mobile barber: public liability that covers the places you work, and cover for the kit in your car.
- Hairdresser or salon: the same main covers, with more attention on colour and chemical services.
How Do I Get Barber Insurance?
Start by writing down the cover your lease or chair agreement asks for. Then work out what your tools, stock and fit-out would cost to replace.
Tell us about your shop and a broker will contact you with your options. Barbershop Insurance is a broker, so we arrange the cover and the insurer issues the policy and pays claims.
Related Cover
Summarise with AI
Open a short summary in ChatGPT, Claude, Gemini or Perplexity.
This is general information only and does not take into account your objectives, financial situation or needs. Cover is subject to the policy terms and the insurer's acceptance.