

A client is nicked by a razor and claims
A cut from a straight razor, a burn from a hot towel or a reaction to beard dye can each turn into a claim. Depending on how your policy is written, public liability or treatment risk cover pays it.
Specialist insurance broker for barbers
We help shop owners, employed barbers, chair renters and mobile barbers compare and arrange public liability, tools cover, shop contents cover and more. Tell us about your shop and a broker will contact you with your options.
Frans du PlessisBroker since 1992 · NIBA Western Australian Broker of the Year 2023
Awards and listings for Frans du Plessis, who founded Grace Insurance in Perth in 2015
 WinnerNIBA (National Insurance Brokers Association) Western Australian Broker of the Year 2023Frans du Plessis
 ListedInsurance Business Elite Brokers 2026Frans du Plessis
 ListedInsurance Business Hot List 2026Frans du Plessis, one of 54 leaders across Australia and New Zealand
Barber insurance in Australia
Most barbers need public liability, which pays injury and property claims from clients and the public, plus cover for their tools. Add treatment risk, cover for harm a shave or colour causes, if you offer those. Shop owners add contents cover for chairs and stock, and employers must hold workers compensation, which pays staff who are hurt at work.
| Cover | Shop owner | Chair renter | Mobile barber |
|---|---|---|---|
 Public liabilityClaims from clients and the public who are hurt, or whose property is damaged, plus your legal costs. | |||
 Professional indemnity and treatment riskClaims that a service caused harm, such as a razor cut, a hot towel burn or a reaction to beard dye. | if you shave or colour | if you shave or colour | if you shave or colour |
 Tools and equipmentTheft of or damage to your clippers, scissors and styling tools. | |||
 Shop contents and fit-outRepairing or replacing chairs, mirrors, stock and the fit-out, meaning the benches and plumbing you put in, after damage the policy covers. | – | – | |
 Workers compensationWages and medical costs for an employee hurt at work. | once you employ staff | – | – |
Employers must hold workers compensation, and each state and territory sets its own rules. Public liability is required by law only for certain occupations in some states and territories, so for most barbers the law leaves it to you.
Your lease, the shop you rent a chair in or a venue can still make it a condition of working there. If you are a sole trader, workers compensation does not cover you, so look at personal accident and illness cover for yourself.
Barbershop insurance claims
A razor nick, a slip, a theft and a leak are common barbershop claims, and the cover that pays depends on what happened.
A cut from a straight razor, a burn from a hot towel or a reaction to beard dye can each turn into a claim. Depending on how your policy is written, public liability or treatment risk cover pays it.
Public liability pays their claim and your legal costs, up to the limit you choose: $5 million, $10 million or $20 million.
Tools and equipment cover, which insurers call general property, pays for the clippers, scissors and styling tools you carry between the shop and your clients.
Contents and fit-out cover pays to repair or replace the chairs, mirrors, stock and fittings. Business interruption covers the income you lose while the shop is closed.
Some policies include treatment risk inside public liability and some list it separately. If you shave, colour or use chemicals, ask us to show you where it sits on your quote before you agree to it.
Barber insurance covers
We arrange each of these for barbers, shop owners and chair renters. Pick the ones that fit how you work and we will go through each one with you.
Covers claims from clients and the public for injury or damage to their property, with limits of $5 million, $10 million or $20 million.
Covers claims that a cut, shave, colour or other service you gave caused harm or loss.
Insurers call it general property. It covers your clippers, scissors and styling tools against theft and damage.
Covers your chairs, mirrors, stock and fit-out, the benches and plumbing you put in, whether you own or lease.
Covers the income you lose while the shop is closed after damage your policy covers, such as a fire.
Covers wages and medical costs for employees hurt at work. Each state and territory sets its own rules.
Covers the costs that follow a hack or data breach, such as an attack on your booking system or client list.
Helps replace your income if an injury or illness stops you working, which matters most when you are self-employed.
Grace Insurance's claims line, 0411 234 878, is open 24 hours, 7 days.
We usually bring you 2 to 12 quotes, so you can compare covers and prices.
We are Corporate Authorised Representative 1008568 of Community Broker Network Pty Ltd, which holds Australian Financial Services Licence 233750.
You can pay your premium, the price of your policy, by the month instead of paying it all at once.
Barbers, shop owners and chair renters
We arrange cover for the people behind the chair, whether you own the shop, work in it or rent a chair in it.
 Shop ownersWe arrange cover for your premises, fit-out and staff, and for the public who come into your shop.
 BarbersWe arrange cover for the work you do in the chair and the tools you use.
 Chair rentersThe shop's policy usually does not cover you. You need your own.
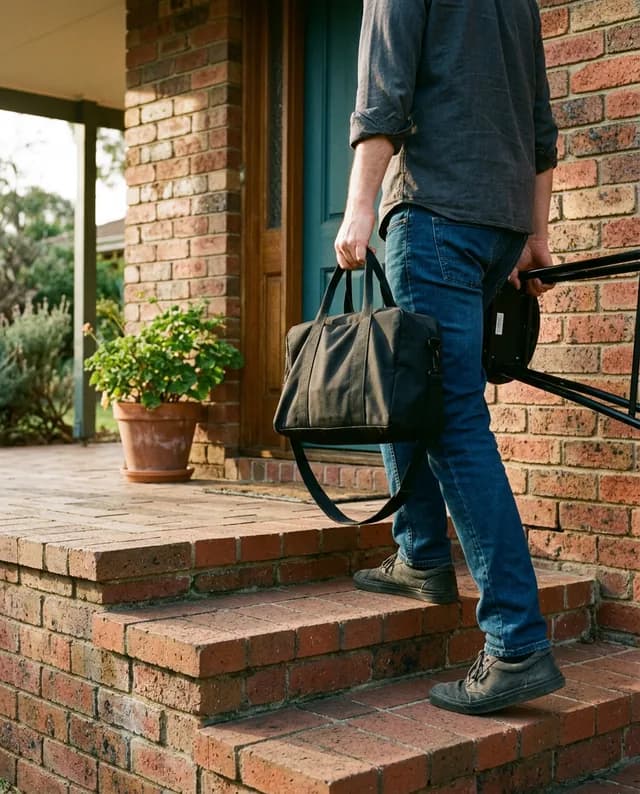 Mobile barbersWe arrange cover for the tools you carry and the work you do in clients' homes.
 Hairdressers and salonsWe arrange the same covers for hairdressers and hair salons.
Your broker
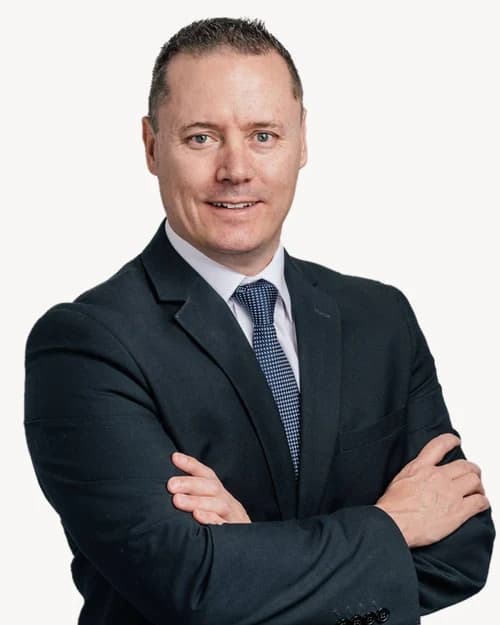
Barbershop Insurance is the barber arm of Grace Insurance, an Australian-owned brokerage that Frans du Plessis founded in Perth in 2015. Frans has worked in insurance broking since 1992.
He wrote Grace's guide to hairdresser and barber insurance in 2019 and updated it in December 2024. Frans works with a team of more than 20 brokers across Australia and New Zealand.
Frans du Plessis · Founder and Director, Grace Insurance
The award and the two listings are Frans's own, not Grace Insurance's or ours.Frans's profile at Grace Insurance →
Barber insurance quote
Fill in the quote form or call us, and tell us how you work. We take your details to insurers, contact you with your options and arrange the one you pick. We aim to reply within 24 hours.
Fill in the form or call us. Say whether you own a shop, work in one, rent a chair, travel to clients or run a salon, and which covers you need.
We can approach more than 160 insurers and ask 2 to 12 of them to quote. Fewer insurers quote on some specialist liability covers, so you may see fewer options.
For each option we set out what it covers, what it leaves out, the limit and the price. If any word on the policy is unclear, ask us.
Pick the option that suits you and we arrange it with the insurer. We can then get your certificate of currency for you.
Barber insurance cost
Your premium, the price of your policy, is set by the insurer and confirmed on your quote. The main things that decide it are the services you offer, the size of your team and the limit you choose. Your claims history, where you work and what your kit is worth count too.
Clipper cuts, razor shaves, colour and chemical work carry different risks, so the insurer asks which you do.
More staff and a higher turnover, your yearly sales, mean more work to insure, and once you employ staff you also need workers compensation.
You choose a $5 million, $10 million or $20 million limit. Check what your shop lease asks for before you pick.
The insurer asks about any claims you have made before and takes them into account when it sets the price.
Your state counts, and so does whether you work in your own shop, from a rented chair or at clients' homes.
The more your clippers, chairs and fit-out would cost to replace, the more there is for the policy to insure.
Through premium funding, a finance company pays the insurer for you. You repay it weekly, fortnightly, monthly, quarterly or every six months.
Barber insurance claims
Call Grace Insurance's claims line on 0411 234 878, open 24 hours, 7 days. We are your advocate: we help you prepare and lodge the claim and deal with the insurer for you. The insurer assesses the claim and decides what the policy covers.
Grace Insurance claims line
24 hours, 7 days
Or email claims@graceinsurance.com.au
Do not book repairs until the insurer agrees, unless the work stops more damage. Keep the invoice and photos if you do.
How claims work →Barber insurance broker
Barbershop Insurance is the barber arm of Grace Insurance, an Australian-owned brokerage. We arrange your cover and explain it before you buy. The insurer takes on the risk, called underwriting: it decides whether to offer you cover, on what terms and at what price.
Tell us what you do and we will contact you with your options. You choose the covers and the limits.
Your landlord can ask for a certificate of currency, and we can get it for you.
A shop owner, a barber and a chair renter each need different covers, so we arrange yours around the way you work.
| Going direct to an insurer | A comparison site | A broker | |
|---|---|---|---|
| Whose policies you see | Only that insurer's own policies. | Policies from the insurers the site lists. | Usually 2 to 12 quotes, from the more than 160 insurers we can approach. |
| Who explains the cover | The insurer's staff, about their own policy. | The site's summaries and the policy documents. | We do, before you buy. |
| Who helps when you claim | You deal with the insurer's claims team. | You deal with the insurer that issued the policy. | We are your advocate and deal with the insurer for you. |
Licence, reviews and complaints
Yes. We are Corporate Authorised Representative 1008568 of Community Broker Network Pty Ltd, which holds Australian Financial Services Licence 233750. Grace Insurance has its own Google reviews, Community Broker Network follows the brokers' code of practice, and complaints can go to AFCA, a free complaints service.
 Grace Insurance on Google
4.9
Grace Insurance, the brokerage we are part of, is rated 4.9 from 81 Google reviews. The reviews come from all of Grace's clients, not only barbers.
Read Grace Insurance's Google reviews →Our licensee, Community Broker Network, is a principal member of NIBA and has adopted the Insurance Brokers Code of Practice. The code sets out how brokers must treat their clients.
Financial Services Guide →Community Broker Network is a member of AFCA, the Australian Financial Complaints Authority. AFCA handles complaints about financial firms, and its service is free to customers.
How to make a complaint →Guides for barbers
Each guide answers one question in full, with the covers, limits and rules that apply to barbers.
Reviewed by Frans du Plessis
Founder and Director, Grace Insurance
Barber insurance FAQ
A shop owner usually starts with public liability, cover for the fit-out and stock, and cover for the clippers and tools. Add business interruption, which pays the income you lose while closed after damage the policy covers. Once you employ staff, workers compensation is required by law.
There is no set price. The insurer prices your policy on what you do, your staff, your turnover and your limit, plus your claims history, location and kit. Your price is confirmed on your quote, and you can pay it by instalments.
Public liability is required by law only for certain occupations in some states and territories, so for most barbers the law leaves it to you. Landlords, shopping centres and shop owners renting out chairs commonly ask for it. Without it, an injury claim from a client is yours to pay.
Yes, because the shop's policy usually does not cover you and a claim from one of your clients would land on you. Get public liability in your own name and cover for your clippers and scissors. The shop owner can ask to see your certificate of currency.
It pays claims from clients and the public who are hurt, or whose property is damaged, because of your business, plus your legal costs. It does not cover your own tools, your own injuries or your employees' injuries. Those need tools cover, personal accident and illness cover, and workers compensation.
It depends on how your policy is written. Some public liability policies include treatment risk, cover for harm caused by the service itself, and some leave it to a separate professional indemnity policy. If you shave, colour or use chemicals, ask us to show you where treatment risk sits on your quote.
Yes, if you employ anyone, with a few state exemptions for very small wage bills. Casual and part-time staff and apprentices count as workers, and each state and territory runs its own scheme. It does not cover you as a sole trader, so look at personal accident and illness cover.
You can choose $5 million, $10 million or $20 million. Start with your lease or chair rental agreement, because a landlord, shopping centre or shop owner can set the minimum you must hold. If nobody sets one, we can talk you through the difference in price between the limits.
Unless you employ staff, the law usually leaves it to you, but you still work on clients every day. Public liability covers claims from clients in their homes and at venues. Tools cover, which insurers call general property, protects the kit you carry in your car.
Usually a certificate of currency, a short document from your insurer that proves your policy is active and shows your covers, limits and dates. Your lease may also set a minimum public liability limit, so check it before you choose. Once your policy is in place, we can get the certificate for you.
Barbershop insurance quote
Tell us how you work and which covers you need, and we aim to reply within 24 hours.