

Key points
- The shop's policy usually does not cover a chair renter.
- You need public liability in your own name.
- Treatment risk cover pays claims about the service you gave.
- Your clippers and scissors need their own cover.
- With no sick pay, personal accident and illness cover is worth adding.
- The shop owner will usually ask for your certificate of currency.
Does the Shop's Insurance Cover a Chair Renter?
Usually not. A policy covers the business named on it, and the shop owner's policy names their business, not yours.
When you rent a chair, you run your own business inside someone else's shop. Your clients and your work are your own, so if your client is hurt or says your work harmed them, the claim comes to you.
Ask the shop owner whether their policy covers renters. Unless the answer is yes, in writing, arrange your own.
What Insurance Does a Chair Renter Need?
A chair renter needs public liability, treatment risk cover and tools cover. Public liability comes first, because it is the cover shop owners ask to see.
- Public liability: claims from your clients who are hurt or have things damaged, with a limit of $5 million, $10 million or $20 million.
- Professional indemnity: its treatment risk cover pays claims that a cut, colour or shave you gave caused harm.
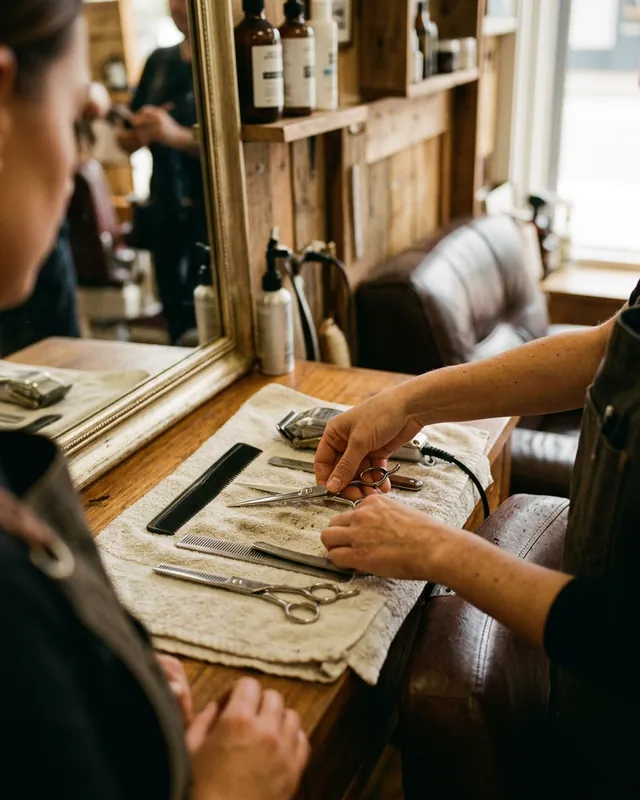
- Tools and equipment: your clippers, trimmers and scissors if they are stolen or damaged, in the shop or on the way home.
- Personal accident and illness: a regular payment while an injury or illness stops you working.
What Will the Shop Owner Ask a Chair Renter For?
Most shop owners ask for a certificate of currency, a short document from your insurer showing your cover is active. Expect to show it before your first day and again each year when you renew.
Check your chair agreement for a minimum public liability limit. If it names a figure, your policy needs to meet it. See certificates of currency explained for what to check before you send yours.
Is a Chair Renter the Shop Owner's Worker?
Sometimes, depending on the arrangement and your state's rules. Workers compensation, the cover for staff hurt at work, can treat someone as a worker even when they are called a contractor or renter.
In NSW, for example, a person is more likely to be a worker if the owner directs their work or supplies their tools. Being paid by the hour or week points the same way. Other states run their own tests, so check with your state's workers compensation authority before a renter starts.
Do Chair Renters Need Cover for Products They Sell?
Yes, if you sell products such as pomade, beard oil or shampoo to clients. If a product you sold causes a rash or damages something, the claim can come to you as the seller.
Products liability pays those claims. It is usually sold with public liability as public and products liability. Check both appear on your policy schedule, the document that lists your covers.
What Covers a Chair Renter Who Cannot Work?
Personal accident and illness cover pays you a regular amount while an injury or illness stops you working. As a chair renter you are usually self-employed, so there is no sick pay.
Workers compensation does not cover a sole trader, and the chair rent is still due while you are off. Ask us to quote personal accident and illness cover alongside your public liability.
What to Do If a Client Claims Against You
Do not admit fault, even if you think the mistake was yours, and tell us within 24 hours. Leave the question of fault to the insurer, which assesses the claim and decides what the policy covers.
Write down what happened, when and where, and take the client's name and contact details. Keep any letters or court papers you receive. See making a claim for the full list of what to have ready.
Does a Chair Renter's Insurance Move With Them?
Yes. A policy in your own name covers your business, so it goes with you when you change shops. Tell us the new address so your policy and certificate stay correct.
If you also cut hair at clients' homes or at events, tell us that too. See insurance for mobile barbers for the cover those places need.
Insurance for Shop Owners Who Rent Out Chairs
Ask every renter for a current certificate of currency and keep a copy. Write a minimum public liability limit into your chair agreement, and check the end date on each certificate every year.
For the cover on the shop itself, see insurance for barbershop owners.
How Does a Chair Renter Get Insured?
Have your chair agreement, the value of your tools and a list of the services you offer ready. Then tell us how you work.
A broker will contact you with your options. See insurance for barbers renting a chair for more on each cover.
Related Cover
Summarise with AI
Open a short summary in ChatGPT, Claude, Gemini or Perplexity.
This is general information only and does not take into account your objectives, financial situation or needs. Cover is subject to the policy terms and the insurer's acceptance.