

Business interruption insurance
Business Interruption Insurance for Barbershops
If a fire or burst pipe closes your shop, contents insurance pays to repair the damage and business interruption pays the income you lose while the work is done.
Rent, staff wages and loan repayments still have to be paid while the shop is closed. Without this cover, they come out of your own pocket.
Cover is subject to the policy terms and the insurer's acceptance.
Reviewed by
Founder and Director, Grace Insurance. Diploma in Broking, Fellow CIP. In insurance broking since 1992.
What business interruption pays for
What Does Business Interruption Cover in a Barbershop?
Business interruption pays the income you lose, and the bills you still owe such as rent and wages, while damage that your property cover pays for keeps your shop closed or slows trade.
A fire closes the shop
A fire damages the shop, and it stays closed while it is stripped out, repaired and refitted. Business interruption pays the profit you would have made over that time, and the rent and wages you still owe.
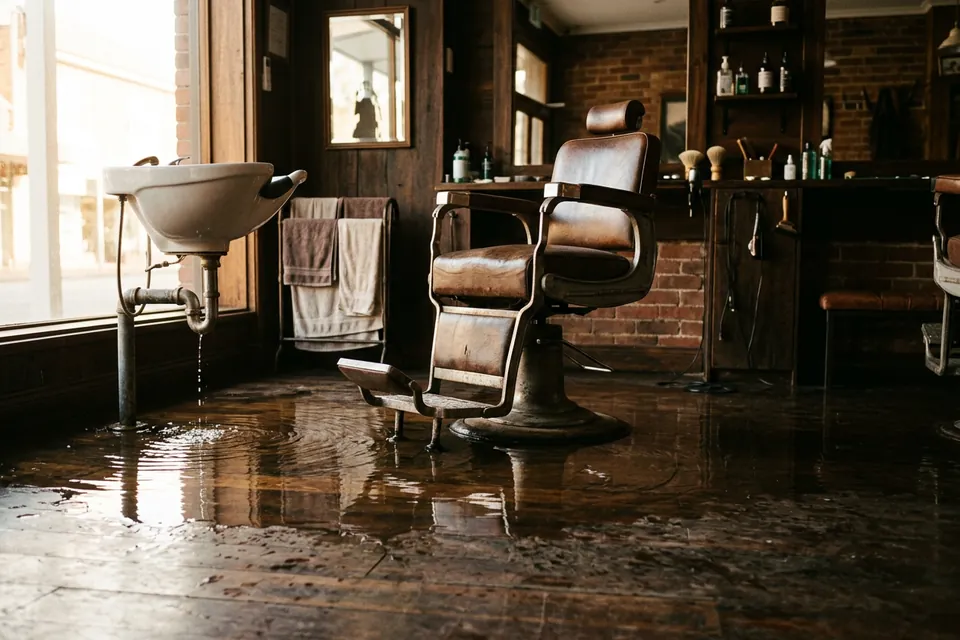
A burst pipe floods the floor
Water through the floor and walls can close a shop while it dries out and is repaired. Your contents insurance pays to fix the damage, and business interruption pays the income you lose while you wait.
Working from somewhere else
If you can keep cutting from a temporary spot, the policy can pay the extra cost of doing that, such as short-term rent, which insurers call increased cost of working.
Damage nearby keeps clients away
Some policies also pay when damage to a nearby property, such as a fire in the shopping centre, stops clients reaching you. Ask us whether a policy includes it before you buy.
When it pays
When Does Business Interruption Pay Out?
It follows a property claim
Business interruption pays out when your shop closes or slows because of damage that your contents and fit-out insurance also covers, such as a fire, storm or burst pipe. In most policies, it does not pay for a closure with no damage behind it.
Illness and quiet trade are not covered
It does not pay because you are sick, because a staff member leaves or because trade is quiet. If you are too sick or hurt to work, that is personal accident and illness insurance.
Disease closures are often left out
Many policies now leave out closures caused by an infectious disease, such as a pandemic shutdown. Check the exclusions, the list of things a policy does not pay for, on your quote before you buy.
Business interruption cost
What Affects the Price of Business Interruption Cover?
Your premium, the price of the policy, depends on how much your shop earns, how long you want the policy to pay, the wages you cover, any waiting time before it pays, your premises and your claims history. The exact figure is confirmed on your quote.
Your gross profit
Insurers work from gross profit, roughly what the shop takes in a year less the cost of the stock you sell. A busier shop has more to lose.
The indemnity period
The indemnity period is how long the policy keeps paying after the damage. A longer period costs more, so choose one that covers a full refit and the time it takes your regulars to come back.
The wages you cover
Many policies let you choose how much of your staff wages to cover, and for how long.
A time excess
Some policies have a time excess, the first hours or days of a closure that the policy does not pay for.
Your premises
The things that set your contents price, such as where the shop is, its security and the building, set this price too.
Your claims history
Recent claims can raise the premium.
You can pay the premium in one go, or spread it with premium funding, where a finance company pays the insurer for you and you repay it weekly, fortnightly, monthly, quarterly or every six months.
Who it is for
Who Needs Business Interruption Insurance?
Any barbershop owner or hairdresser or salon owner with rent, staff wages or loan repayments to pay should have it, because those bills keep coming while a damaged shop is closed.
A mobile barber with no shop has no premises to close, so tools and equipment insurance and personal accident and illness insurance usually matter more.
Related covers
Other Insurance for Barbershop Owners

Shop Contents and Fit-out
Covers your chairs, mirrors, stock and fit-out, the benches and plumbing you put in, whether you own or lease.
Read about shop contents and fit-out →
Personal Accident and Illness
Helps replace your income if an injury or illness stops you working, which matters most when you are self-employed.
Read about personal accident and illness →
Public Liability
Covers claims from clients and the public for injury or damage to their property, with limits of $5 million, $10 million or $20 million.
Read about public liability →Business Interruption FAQ
Business Interruption Questions
No. It pays when damage to the shop stops trade. If illness or injury stops you working, that is personal accident and illness cover.
Usually not. Many policies now leave out closures caused by an infectious disease. Check the exclusions, the list of things the policy does not pay for, on your quote.
It pays for the indemnity period, the length of time the policy keeps paying after the damage. You choose that period when you buy. Pick a period long enough to repair the shop and win your clients back.
Usually not. It is sold with property cover, such as contents and fit-out insurance, because it only pays after damage that your property cover pays for. We can quote the two together.
It can. Many policies cover the wages you keep paying while the shop is closed, up to the amount and the period you choose.
Business interruption quote
Get a Business Interruption Quote
Tell us your rent, staff and how long a refit would take, and a broker will contact you with your options.
1800 556 777Monday to Friday, 8:30am to 5:00pm Perth time