

Barber public liability insurance
Public Liability Insurance for Barbers
If someone is injured in your shop, or their property is damaged, they can claim against you. Public liability pays that claim and the legal costs of defending it.
Your landlord will usually want proof of it before you open, and shop owners ask chair renters for it too.
Cover is subject to the policy terms and the insurer's acceptance.
Reviewed by
Founder and Director, Grace Insurance. Diploma in Broking, Fellow CIP. In insurance broking since 1992.
What public liability pays for
What Does Public Liability Cover in a Barbershop?
Public liability covers injury to people who do not work for you, and damage to their property: clients, people waiting, delivery drivers and anyone who walks through the door.
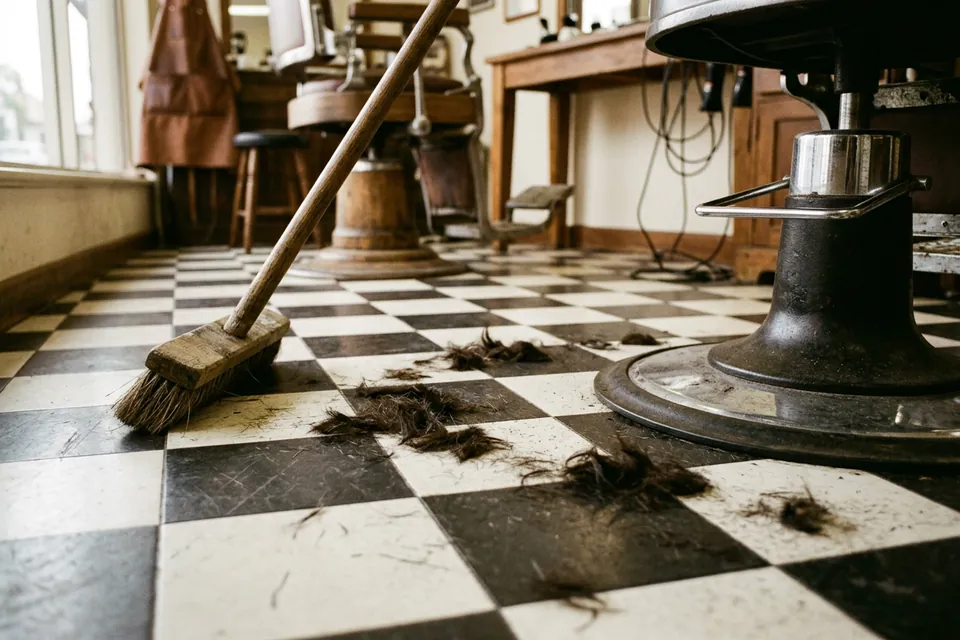
A client slips on clippings
Cut hair on a tiled floor is easy to slip on. If a client falls and breaks a wrist, public liability pays their claim for medical costs and lost income. It also pays the legal costs of defending it.
Dye ends up on a client's clothes
A splash of beard dye on a white shirt, or hair oil spilled on a leather jacket, is damage to their property. Public liability pays to clean, repair or replace it.
Someone trips in the waiting area
A friend waiting for a client trips on a clipper cord or a loose mat. They are not your client, but public liability still covers their claim.
You cut hair outside the shop
Public liability covers your business, not just the shop address, so it can cover your work at a wedding, a client's home or a temporary event stall. Make sure the policy lists that work.
Choosing your limit
How Much Public Liability Cover Do Barbers Need?
Your lease sets the minimum
Your limit is the most the insurer will pay for one claim, and you need at least the limit your lease or shop owner asks for. Read the insurance clause in your lease before you choose, because it often sets the minimum limit you must hold. We can arrange $5 million, $10 million or $20 million.
Your landlord may need to be noted
Landlords and shopping centres often write a minimum limit into the lease. Some also ask to be noted on the policy as an interested party, which tells the insurer they have a stake in your cover.
The number of visitors sets the rest
Above that minimum, think about who comes through the door. A busy shop with walk-in clients, children and a waiting area has more people who could be injured than a one-chair studio.
Ask us to quote two limits side by side and you can see the difference in price before you choose.
Compare two limits
Products liability
Does Public Liability Cover Products I Sell?
What products liability covers
Products liability is the part of the policy that covers injury or damage caused by something you sell or supply. In Australia it is normally sold with public liability, as public and products liability, so check both are listed on yours.
When it matters
It matters if you sell pomade, beard oil, shampoo or clippers over the counter. If a client reacts to a beard oil they bought from you, the claim can come to you as well as the maker.
Own label or imported
If you import products yourself or sell them under your own label, tell us, so the insurer can price your products liability correctly.
Renting a chair
Do Chair Renters Need Their Own Public Liability?
01Your own business, your own cover
Yes. As a chair renter you run your own business inside someone else's shop, and the shop's policy usually covers the owner's business, not yours. If your client slips or has a reaction, the claim comes to you.
02Show your certificate of currency
The shop owner will often ask to see your certificate of currency, a short document from your insurer that proves your policy is active. Keep a copy on your phone.
03If you own the shop
If you own the shop, ask every renter for a certificate of currency, because a claim against a renter with no cover can end up with you. If you rent a chair, see insurance for barbers renting a chair for the other covers a renter needs.
What is not covered
What Public Liability Does Not Cover
Public liability does not cover you, your staff or your own property, only other people and their property. It usually leaves out:
Injury to your own employees, which is workers compensation.
Your own tools, chairs and stock, which is tools and equipment insurance and contents and fit-out insurance.
A claim that the cut, shave or colour itself caused the harm, if your policy leaves that to professional indemnity and treatment risk.
Your own injury or illness, which is personal accident and illness insurance.
Damage you cause on purpose, and fines or penalties.
Public liability cost
What Affects the Price of Public Liability?
Your premium, the price of the policy, depends on your limit, turnover, where you work, the services you offer, the products you sell and your excess. The exact figure is confirmed on your quote.
The limit you choose
A $20 million limit costs more than $5 million, because the insurer could pay out more.
Your turnover
Insurers use what the business takes in a year as a guide to how many clients you see.
Where you work
A street shop, a shopping-centre site, a home studio and mobile work each carry different risks.
The services you offer
Straight-razor shaves, colour and chemical work such as perms and straightening can add to the price compared with clipper cuts alone.
Products you sell
Selling retail stock adds to your products liability risk, and selling your own label or imported products adds more.
Your excess and claims history
The excess is the amount you pay towards each claim. A higher excess usually lowers the premium, and recent claims can raise it.
You can pay the premium in one go, or spread it with premium funding, where a finance company pays the insurer for you and you repay it weekly, fortnightly, monthly, quarterly or every six months.
For how premiums are worked out, read how much barber insurance costs.
Who it is for
Who Needs Public Liability Insurance?
Anyone running a barbering or hairdressing business that serves the public should have it. That includes barbershop owners, barbers who take their own clients, mobile barbers, and hairdressers and salons.
For most businesses the law leaves public liability up to you, though some states and territories require it for certain jobs. Landlords, shop owners and event organisers will still ask for it, so have it in place before you sign a lease or book an event.
Hairdressers and salons
Is Public Liability Insurance for Hairdressers the Same?
Yes. Public liability for hairdressers pays the same kinds of claim as it does for barbers, such as a client who slips on a wet floor or a coat marked by colour.
If a client says the colour, bleach or razor itself harmed them, that is a claim about your service. Some policies pay it under public liability, and others leave it to treatment risk cover, which pays when a service harms a client, so check which way your quote is written.
We arrange cover for hair and barber businesses in every state and territory. Colour and chemical work such as perms and straightening can add to the price, so tell us the services you offer. See insurance for hairdressers and salons for the other covers a salon needs.
Hairdresser and salon insuranceRelated covers
Other Insurance for Barbers
Professional Indemnity
Covers claims that a cut, shave, colour or other service you gave caused harm or loss.
Read about professional indemnity →Tools and Equipment
Insurers call it general property. It covers your clippers, scissors and styling tools against theft and damage.
Read about tools and equipment →
Shop Contents and Fit-out
Covers your chairs, mirrors, stock and fit-out, the benches and plumbing you put in, whether you own or lease.
Read about shop contents and fit-out →Public Liability FAQ
Public Liability Questions for Barbers
Usually not by law, though some states and territories require it for certain jobs. A lease, a shopping centre or the shop you rent a chair in can make it a condition. Without it, a claim is paid out of your own pocket.
Choose at least the minimum your lease or shop owner sets, and more if a lot of people come through your shop. We can arrange a limit, the most the insurer pays for one claim, of $5 million, $10 million or $20 million.
It can. Some public liability policies cover injury caused by the service itself, and others leave it to treatment risk cover, which pays when a cut or shave hurts a client. Ask us which way a policy is written before you buy.
Usually, if the policy lists mobile or home visits as part of your business. Tell us where you work when you ask for a quote so the policy matches.
Yes, if you cut hair for the public. A sole trader can be sued like any shop, and a lease or the shop you rent a chair in may ask for cover. Workers compensation does not cover a sole trader, so your own injury needs personal accident and illness cover.
It depends on your limit, turnover, where you work, the services you offer and any products you sell. We confirm the premium on your quote, and you can pay in instalments through premium funding. A $20 million limit costs more than a $5 million limit, because the insurer could pay out more.
Yes. Once your policy is in place, ask us and we will arrange a certificate of currency. It is the document from your insurer that proves your cover is active and shows your limit.
Public liability quote
Get a Public Liability Quote
Tell us how you work and the limit your lease asks for, and a broker will contact you with your options.
1800 556 777Monday to Friday, 8:30am to 5:00pm Perth time